Personal Finance Tips for 2026: A Beginner’s Money Playbook
Solid personal finance tips do not require a finance degree, a six-figure salary, or hours of spreadsheet wrangling. They require a handful of repeatable habits and the discipline to keep them. In 2026, with digital wallets everywhere and interest rates finally stabilizing, there has never been an easier time for a beginner to take control of money.
This playbook is written for people who feel behind: recent graduates, new parents, career switchers, and anyone who has ever avoided opening a banking app out of dread. We will move from mindset to mechanics to the exact tools that make the habits stick.
The Mindset Behind Great Personal Finance Tips
Money management is a skill, not a personality trait. People who feel “bad with money” usually just lack a system, not willpower. The first shift is to stop treating budgeting as punishment and start treating it as permission to spend without guilt.
A budget tells your money where to go before the month spends it for you. That single reframe turns anxiety into a plan you actually look forward to reviewing.
Start with the 50/30/20 rule
The classic framework splits take-home pay into three buckets. It is flexible enough for almost any income and simple enough to remember in the checkout line.
- 50% needs: rent, groceries, utilities, transport, minimum debt payments.
- 30% wants: dining out, streaming, hobbies, travel.
- 20% future: savings, investing, extra debt payoff.
Build Your Emergency Fund First
Before investing a single dollar, stockpile a cash cushion. The Federal Reserve reports that a large share of households still could not cover a modest surprise expense without borrowing, and that fragility is exactly what an emergency fund fixes.
Aim for one month of essential expenses to start, then stretch toward three to six months. Keep it in a separate high-yield savings account so it is reachable but not tempting.
How much should a beginner save each month?
If 20% feels impossible, start at 5% and increase it by one percentage point every payday until it stings a little. Automation makes this painless, because the transfer happens before you ever see the money.
Master Digital Payments Without Losing Track
Peer-to-peer apps have replaced cash for splitting bills, paying babysitters, and reimbursing friends. They are convenient, but casual tapping hides how fast small amounts add up. Setting up your accounts correctly prevents that leak.
If you are new to mobile payments, this practical Cash App guide walks through security settings, instant transfer fees, and how to avoid the most common beginner mistakes.
Weekly money habits that compound
- Check every account balance once a week for five minutes.
- Review one spending category and ask if it reflects your values.
- Move any surplus into savings before the weekend.
- Note one thing you overspent on and plan around it next week.
A Simple Framework for Beginners
Here is a comparison of the three money moves beginners obsess over, and where each one actually belongs in your journey.
| Money Move | When to Start | Typical Return | Priority |
|---|---|---|---|
| Emergency fund | Immediately | Peace of mind | Highest |
| High-interest debt payoff | Alongside fund | 15–25% saved | High |
| Retirement investing | After cushion | 7–10% long term | Medium |
| Individual stocks | Much later | Highly variable | Low |
Notice that flashy investing sits at the bottom. Beginners who skip the boring steps almost always regret it during the first real emergency.
Invest in learning, not just assets
The highest-return investment early on is often knowledge. Whether that means a book, a course, or hiring help, guidance pays dividends. Families who want their children to build the same discipline sometimes bring in reputable service experts to teach the fundamentals early, and money habits deserve the same intentional coaching.
Avoid the Traps That Sink Beginners
Most financial setbacks are not dramatic; they are slow leaks. Watch for these common ones and you will outperform the majority of your peers.
- Lifestyle creep: every raise gets absorbed by nicer wants.
- Minimum-payment trap: paying only the minimum keeps debt alive for years.
- Subscription drift: forgotten free trials quietly renew at full price.
- No-goal saving: money without a purpose gets spent on impulse.
My favorite original tip: name your savings accounts after their goals, like “Barcelona 2026” or “Baby fund.” A named account is far harder to raid than a nameless pile of cash, because spending it means canceling a dream.
Turn Good Habits Into Long-Term Wealth
Once your emergency fund is stocked and high-interest debt is shrinking, the next chapter is growth. Beginners often overthink this stage, but the winning move is boringly simple: invest consistently in low-cost, diversified funds and let compounding do the heavy lifting over decades.
Time in the market beats timing the market almost every time. A twenty-five-year-old who invests a modest amount monthly can end up ahead of a forty-year-old who invests far more, purely because those early dollars compound the longest.
The three-account starter system
- Checking: for bills and daily spending, kept lean on purpose.
- High-yield savings: for your emergency fund and short-term goals.
- Investment account: for retirement and long-term wealth.
Route your paycheck automatically across these three the day it arrives. Automation removes willpower from the equation, and removing willpower is how ordinary people quietly build extraordinary security over time.
Revisit your plan once a year, ideally on a memorable date like your birthday. Check whether your savings rate can rise, whether fees have crept up, and whether your goals still reflect the life you actually want.
Frequently Asked Questions
What is the first personal finance step for a total beginner?
Track every dollar for 30 days without judging yourself. You cannot fix what you cannot see, and one month of honest data reveals exactly where your money actually goes versus where you assume it goes.
How do I stick to a budget when my income is irregular?
Budget on your lowest realistic month and treat surplus income as bonus savings. Pay yourself a steady “salary” from a buffer account so lean weeks feel calm instead of chaotic.
Are budgeting apps better than a spreadsheet?
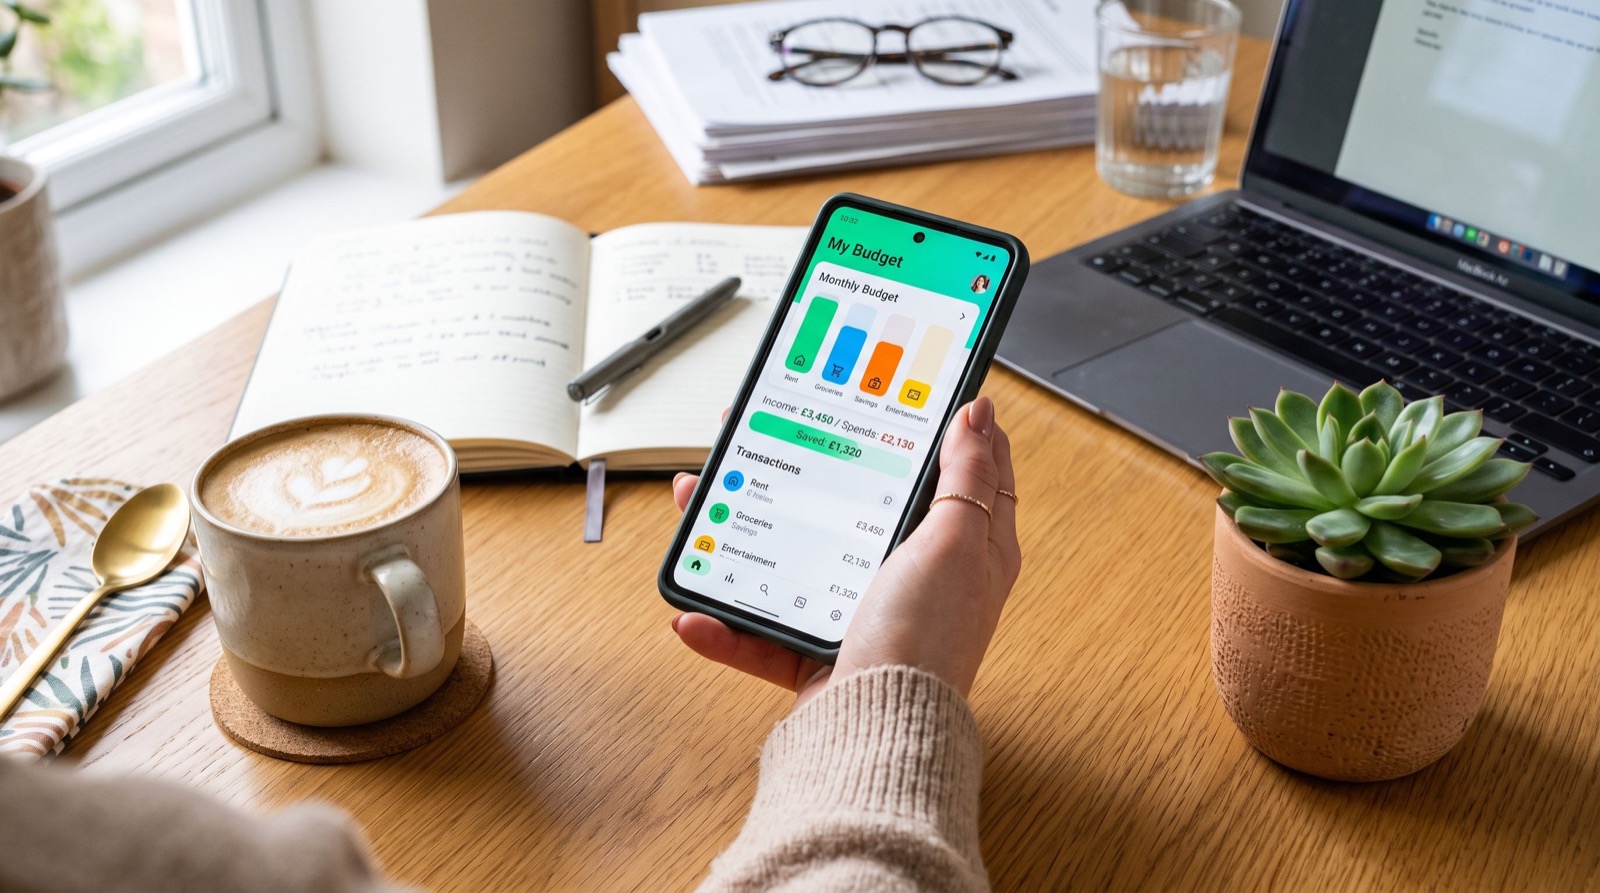
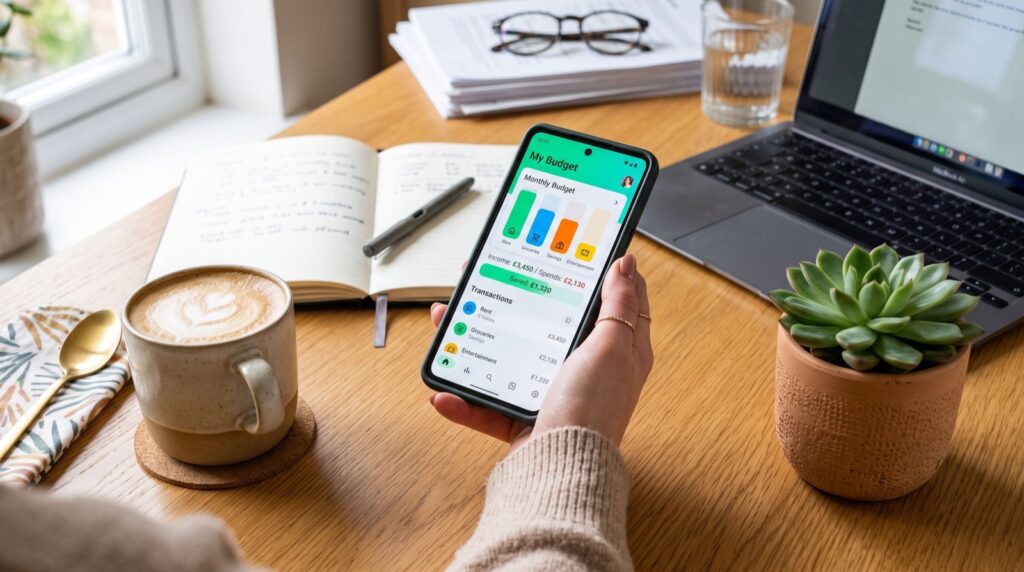
Both work; the best one is the one you open consistently. Apps win on automation and reminders, while spreadsheets win on control, so beginners often start with an app and graduate to a hybrid.
How long until good money habits pay off?
Most people feel calmer within one month and see meaningful savings within three. Real wealth-building takes years, but the reduced stress arrives almost immediately once a system is in place.
Your Next Move
The best personal finance tips are worthless until you act on one of them today. Pick a single habit from this playbook, automate it before you close this tab, and let momentum carry the rest. For more beginner-friendly guidance and app walkthroughs that keep your 2026 goals on track, dig deeper into trusted personal finance tips and start building the future you actually want.